You’re one click away from better coverage. Start your quote with Blue Marsh today!
For a contractor or tradesperson, your truck or van does a lot more than get you from one job to the next.
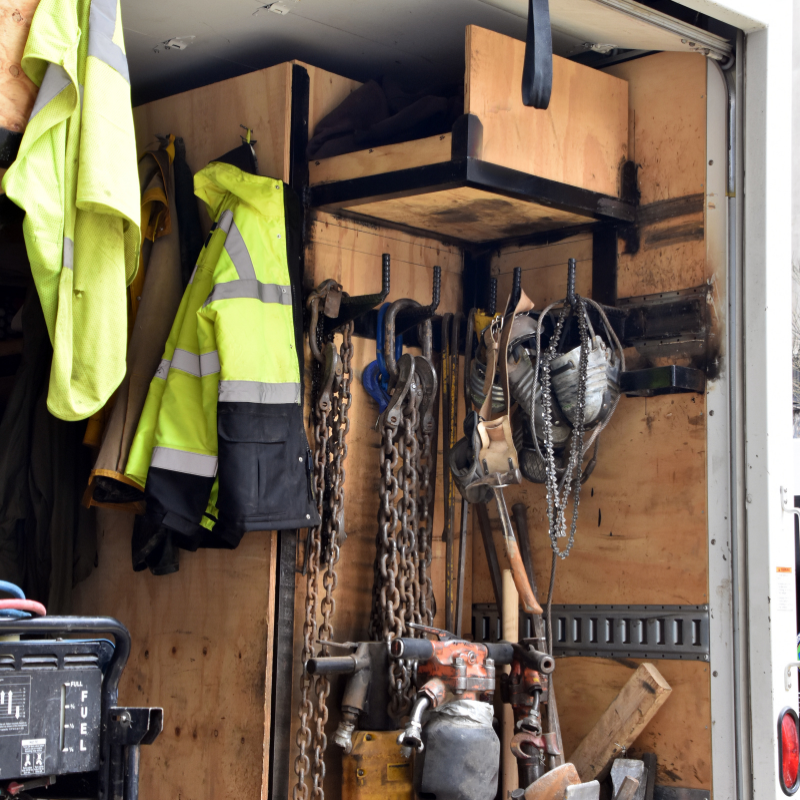
It may carry thousands of dollars in tools, equipment, supplies, and materials you rely on every day to keep your business running.
Think about what’s in your vehicle right now:
- Power and hand tools
- Ladders
- Testing and diagnostic equipment
- Specialty tools
- Portable machinery
- Materials and supplies
Now imagine your truck is involved in a serious accident—or someone breaks into it overnight.
You have commercial auto insurance, so everything in the truck is covered, right?
That’s an assumption you don’t want to make.
Commercial Auto Insurance and Your Tools Are Two Different Things
Your commercial auto policy is designed primarily to protect your business vehicles and provide liability protection related to their use, depending on the coverage you’ve purchased.
But the tools, equipment, and other business property riding inside your vehicle may require different coverage.
For example, let’s say you’re a Pennsylvania contractor with $20,000 worth of equipment in your work van.
After an accident, your commercial auto insurance may cover the damage to the van itself, subject to your policy’s coverage and deductible.
But that doesn’t necessarily mean you have $20,000 of coverage for everything that was damaged inside it.
That’s where business owners can run into an expensive surprise.
What Insurance Covers Tools in a Work Truck?
One type of coverage commonly used to protect mobile business property is inland marine insurance.
Don’t let the name fool you—it doesn’t mean we’re talking about boats!
Inland marine coverage can help protect certain business property that moves between locations rather than remaining at one permanent address.
For contractors and tradespeople, that could include eligible:
- Tools
- Portable equipment
- Machinery
- Testing equipment
- Equipment transported to jobsites
- Other business property that travels with you
Exactly what’s covered will depend on your specific policy, limits, deductibles, exclusions, and other terms.
That’s why we want to know what you’re carrying around every day—and what it would actually cost you to replace it.
Try the “Empty Truck” Test
Here’s a quick exercise for any contractor, plumber, electrician, HVAC company, landscaper, or other mobile business.
Open your work truck or van and ask:
If this vehicle were completely empty tomorrow, how much would it cost to replace everything that’s currently inside?
Start adding it up.
That $500 tool here and $1,000 piece of equipment there can quickly turn into $10,000, $20,000, or considerably more.
And don’t forget all the smaller items you’ve purchased over the years. They may not seem expensive individually, but replacing everything at once could create a major expense for your business.
What About Equipment You’ve Added to the Vehicle?
The contents of your vehicle aren’t the only thing to consider.
Many commercial vehicles are customized specifically for the business using them.
You may have added:
- Permanent shelving
- Toolboxes
- Ladder racks
- Refrigeration equipment
- Generators
- Compressors
- Cranes or lifts
- Other specialized equipment
If you’ve invested thousands of dollars outfitting a vehicle for your business, make sure your insurance agent knows.
A truck that originally cost $45,000 could represent a much larger investment after you’ve customized it for your operations.
Your commercial auto insurance should reflect how the vehicle is actually being used and equipped today—not necessarily how it looked the day you bought it.
Your Tools Aren’t Always in the Truck, Either
Where else does your business keep equipment?
Maybe you unload your tools into a detached garage every night. Perhaps you rent a storage unit. Maybe equipment is kept in a trailer, warehouse, shed, or another location.
Where your business property is located can matter when it comes to insurance.
Don’t assume your coverage automatically follows everything your business owns wherever you decide to store it.
If you’ve changed where you keep tools, equipment, inventory, or other valuable business property, it’s worth letting us know.
When Was the Last Time You Added Up Your Equipment?
Business owners don’t usually purchase all their tools at once.
You buy new equipment as the business grows. You replace older tools. You invest in better technology. You add another truck and outfit it for a new employee.
Over several years, the value of your equipment can increase significantly without you realizing it.
That’s why it’s a good idea to periodically ask:
If I had to replace all of this tomorrow, would my current insurance be enough?
If you don’t know the answer, that’s a good reason to review your coverage.
Let Blue Marsh Take a Look
At Blue Marsh Insurance, we help Pennsylvania contractors and business owners protect more than just their work vehicles. We can help you look at the bigger picture—including the tools, equipment, and other property your business depends on every day.
If you’ve added new equipment, customized your commercial vehicles, or haven’t reviewed your tools and equipment coverage recently, give our commercial insurance team a call.
We’ll help you understand what your current insurance covers and determine whether anything needs to be updated.
Your truck gets you to the job. Your tools allow you to do it. Make sure you’re thinking about protecting both.
A little more about Blue Marsh Insurance…
When he founded Blue Marsh, Tom Davenport wanted to create a different kind of insurance company. One that’s built on personal relationships and a local presence. One where you, the customer, feel more like a friend.
As an independent insurance agency, Blue Marsh Insurance represents a carefully selected group of financially strong, reputable insurance companies. Therefore, we are able to offer you the best coverage at the most competitive price.
If you’re interested in starting a quote online or having us take a look at your current policies, click here!