You’re one click away from better coverage. Start your quote with Blue Marsh today!
We can help with Medicare!
No one wants their family worrying about money while they’re grieving.
Unfortunately, funerals, medical bills, outstanding debts, and other expenses don’t disappear when someone passes away. If there isn’t enough savings or life insurance available, those costs may become the responsibility of the people left behind.
That’s where final expense insurance may help.
But is final expense insurance something you actually need? And how is it different from other types of life insurance?
Here’s what you should know.
What Does Final Expense Insurance Cover?
Final expense insurance is a form of life insurance designed to leave a relatively modest death benefit to your beneficiary after you pass away.
Despite the name, the money generally isn’t earmarked exclusively for your funeral. Your beneficiary may be able to use the death benefit for a variety of needs, depending on the policy and circumstances, including:
- Funeral, burial, or cremation expenses
- Medical bills
- Credit cards or other outstanding debts
- Household bills
- Legal or estate expenses
- Other financial needs your family may face
In other words, final expense insurance can provide your loved ones with money at a time when additional expenses may be the last thing they want to worry about.
Who Should Consider Final Expense Insurance?
Final expense insurance can make sense for someone who wants to leave money specifically to help with expenses after their death but doesn’t necessarily need a large life insurance policy.
For example, perhaps your mortgage is paid off, your children are grown, and replacing decades of income is no longer a concern. However, you don’t have enough savings set aside to comfortably cover funeral expenses and other final bills.
A smaller permanent life insurance policy could potentially fill that gap.
Final expense coverage may be worth exploring if you:
- Have little or no life insurance
- Are concerned about your family paying for your funeral
- Have limited savings available for end-of-life expenses
- Want coverage that is designed to remain in place for life, provided policy requirements are met
- Are looking for a smaller death benefit rather than a large traditional life insurance policy
The important thing is determining whether it actually fills a need in your financial plan.
How Much Final Expense Insurance Should You Have?
There’s no magic number.
Instead of choosing an amount at random, think about what your family could realistically have to pay after you pass away.
Consider potential funeral or cremation expenses, medical bills, outstanding debts, and other immediate financial obligations.
Then look at what you already have.
Do you have savings specifically set aside? Existing life insurance? Other financial resources your family could access?
The difference between what your family might need and what you already have available can give you a better idea of whether additional coverage makes sense.
Is Final Expense Insurance the Same as Life Insurance?
Yes. Final expense insurance is a type of life insurance.
The term “final expense” generally refers to policies designed with a smaller death benefit intended to help with expenses associated with someone’s death.
That’s different from purchasing a larger life insurance policy to accomplish goals such as replacing your income, paying off a mortgage, providing for young children, or supporting a spouse for many years.
That’s also why it’s important not to assume you need final expense insurance simply because you’re getting older. You may already have adequate protection through another life insurance policy or other financial resources.
On the other hand, you may discover there’s a gap you hadn’t considered.
Can You Get Final Expense Insurance Without a Medical Exam?
Depending on the insurance company and policy, you may be able to.
Some final expense policies use simplified underwriting, meaning you may answer health questions without completing a traditional medical exam.
Other products may offer guaranteed-issue coverage with different requirements.
However, “no medical exam” doesn’t always mean everyone automatically qualifies for the same coverage. Policy availability, premiums, waiting periods, graded benefits, and other provisions can vary significantly.
This is one reason it’s helpful to compare your options instead of choosing a policy based solely on an advertisement promising easy approval.
What If I Already Have Life Insurance?
You may not need another policy. Start by reviewing your existing coverage and asking an important question:
What was this policy originally meant to accomplish—and does it still accomplish that today?
Your financial situation may look very different than it did when you purchased your life insurance.
Your mortgage balance may be lower. Your children may now be financially independent. Your income may have changed. Or perhaps an older policy no longer provides as much protection as you thought.
Rather than automatically adding another policy, a life insurance review can help determine whether your current coverage is enough.
What Happens If I Don’t Have Life Insurance or Money Saved for a Funeral?
Ultimately, someone will still need to pay those expenses.
Without adequate savings or life insurance, surviving family members may have to use their own money or find another way to cover funeral costs and other immediate bills.
That’s what final expense planning is really about.
It isn’t necessarily about leaving behind a large inheritance. It’s about making sure the people you love aren’t suddenly faced with expenses they weren’t prepared to handle.
Is Final Expense Insurance Worth It?
It can be—but the answer is different for every person.
Instead of asking whether final expense insurance is “good” or “bad,” ask yourself:
If I passed away tomorrow, would my family have enough readily available money to take care of my funeral and other final expenses without creating a financial hardship?
If you’re not confident about the answer, it’s worth having a conversation.
Talk to Blue Marsh About Your Life Insurance Options
At Blue Marsh, we can help you look at the bigger picture.
Final expense insurance may be the right solution, but it may also make more sense to consider another type of life insurance based on your age, health, family, financial responsibilities, existing coverage, and budget.
As an independent insurance agency, we can help you explore your options and determine what type of protection makes sense for you.
The goal isn’t simply to buy another insurance policy. It’s to make sure the people you love have a plan when they need it most.
Ready to take a look at your options? Contact Blue Marsh Insurance today for a complimentary life insurance review.Ready to see how affordable life insurance could be?
Request your complimentary life insurance proposal here!
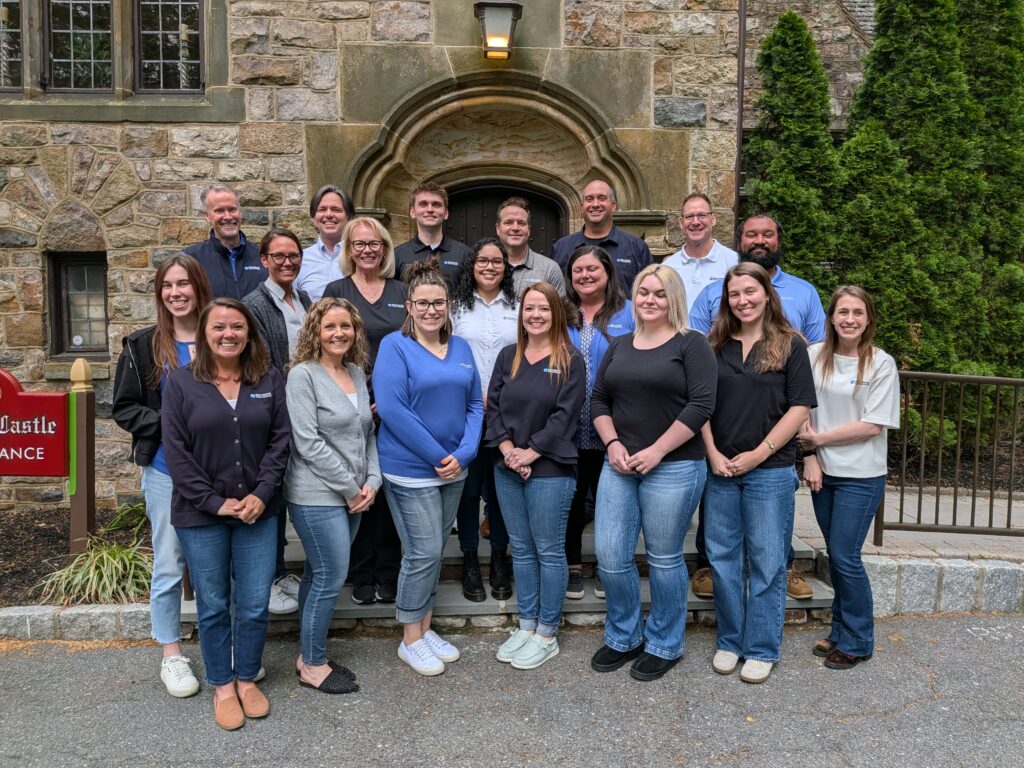
A little more about Blue Marsh Insurance…
When he founded Blue Marsh, Tom Davenport wanted to create a different kind of insurance company. One that’s built on personal relationships and a local presence. One where you, the customer, feel more like a friend.
As an independent insurance agency, Blue Marsh Insurance represents a carefully selected group of financially strong, reputable insurance companies. Therefore, we are able to offer you the best coverage at the most competitive price.
If you’re interested in starting a quote online or having us take a look at your current policies, click here!